Commercial Mortgage Broker in Bristol & the South West

Commercial finance, structured properly from the outset

We arrange commercial mortgages for business owners and property investors, from owner-occupied premises to semi-commercial property and complex refinancing.

No obligation, just clear advice, and never rushed
“
★★★★★

Ed has always been very knowledgeable on all different mortgages be it residential, HMO, BTL, commercial, which having a diverse portfolio is exactly what I require. Also prompt with mortgage applications and updates while the mortgage proceeds. Always very happy to use this company.

Claire Adams · Google review

Verified Adviser badge

Rated 9.8 out of 10 by clients on Verified Adviser

PROPERTY TYPES

What are you looking to finance?

A commercial mortgage is a loan secured on property used for business purposes, such as offices, shops, warehouses or mixed-use buildings. Businesses use one to buy their own premises, investors use one to buy property let to other businesses, and owners can use one to refinance or release equity.

Commercial mortgages can cover a wide range of properties and situations. Whether you’re buying premises for your own business, investing in commercial property or refinancing something you already own, the right lender will depend on the property, the numbers and what you’re trying to achieve.

Commercial mortgage broker in Bristol arranges a commercial mortgage on business premises

Buying Business Premises

For businesses looking to buy the premises they trade from, including offices, retail units, warehouses, surgeries and other commercial property.

Read our guide to buying business premises in Bristol.

Busy commercial shopping area in Bristol city centre with a glass-roofed building at sunset

Commercial Investment

For investors purchasing or refinancing commercial property that is let, or intended to be let, to another business. Landlords with residential lettings can see our buy-to-let mortgages.

Semi-commercial building in Bristol with a shop on the ground floor and accommodation above

Semi-commercial Property

For mixed-use properties combining commercial and residential space, such as shops with flats or accommodation above. This can include conversion or refurbishment projects.

Modern commercial office building with a glass frontage in Bristol

Commercial Remortgage

For businesses and investors looking to refinance an existing commercial mortgage, restructure borrowing or review their current arrangements.

Independent shopfront with outdoor planting on a Bristol high street

Capital Raising

For commercial property owners looking to release equity from an existing property for another business or investment purpose. Where funding is needed quickly, a short-term bridging loan can also be arranged while longer-term finance is put in place.

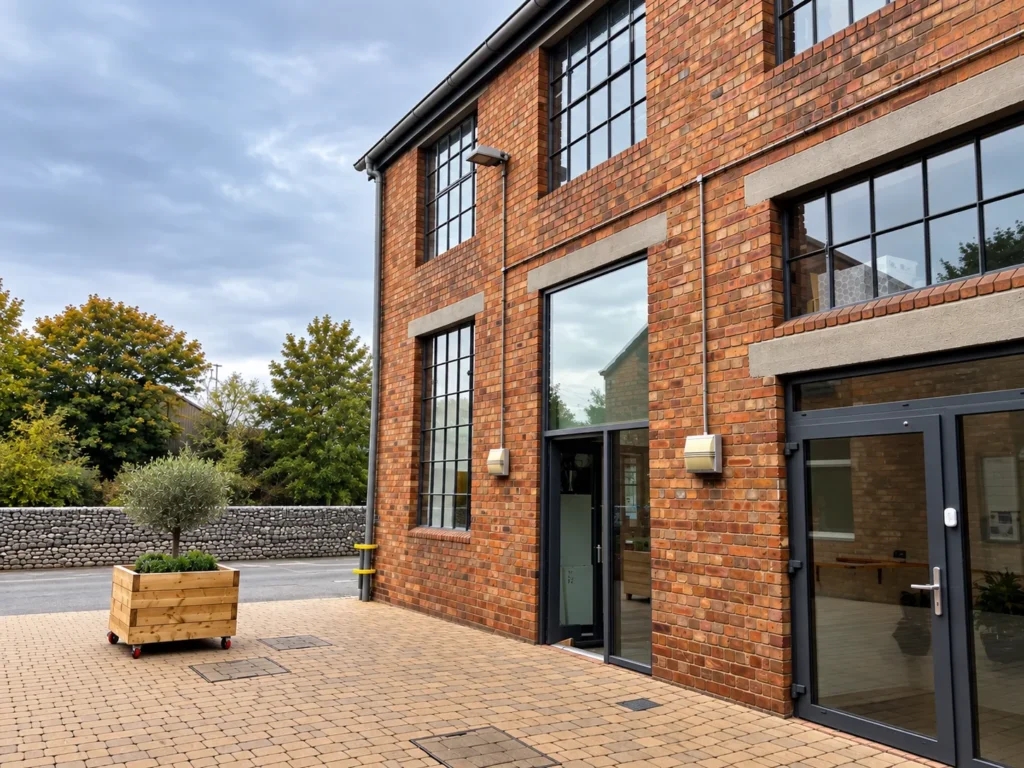
Red brick commercial building at Paintworks in Bristol

Specialist Property

For properties that don’t fit neatly into standard commercial lending, including certain hospitality, healthcare, leisure and other specialist premises.

Where timing is tight, such as an auction purchase or a chain break, bridging finance can secure the property while your commercial mortgage is arranged. Our guide, Bridging loans explained, sets out what it costs and how the exit works.

SPEAK TO US

Already have a property in mind?

If you’ve found a property and want to move quickly, the sooner we understand the details, the sooner we can confirm what’s realistic. Contacting Ed Haupt, founder of Haupt & Co, is the quickest way to establish the terms available to you.

★★★★★
“I can’t recommend Ed and Haupt & Co highly enough.”
Courtney Gallagher · Google review

Commercial Mortgage Calculator

Commercial Mortgage Repayment Calculator

Explore what monthly repayments could look like using illustrative interest rates.

70–75% Typical maximum LTV on suitable cases
25–40% Typical deposit / equity
5–8% Illustrative modelling range

Choose what you are financing, then adjust the property value, deposit and mortgage term.

Illustrative modelling range: 5%–8%. These are modelling assumptions only, not current market rates or a quotation from Haupt & Co. Your actual rate may fall outside this range, and specialist or higher-risk cases can exceed 8%. Assumptions last reviewed: September 2026.

Repayment type
Adjust assumptions

Your Repayment Illustration

These are estimates to help you plan. For a full illustration based on your circumstances, contact us.

30% Deposit / Equity 70% Mortgage
Loan amount modelled £350,000
Loan-to-value 70%
Estimated monthly repayment £2,310 – £2,928
Illustrative modelling range 5.00% – 8.00%
How we calculated this
  • Loan amount: property value minus deposit or equity.
  • LTV: loan amount divided by property value.
  • Repayment: standard monthly amortisation using the selected term and each illustrative rate.
  • Interest only: annual interest divided by 12; the capital is not reduced.
  • Investment coverage: annual rent divided by annual interest at the illustrative stress rate. Capital repayments and property costs are excluded.

Assumptions used in this calculation:

  • Loan amount modelled:
  • Deposit / equity:
  • Loan-to-value:
  • Term:
  • Repayment basis:
  • Illustrative rates modelled:
  • Annual rent modelled:
  • Rental-coverage stress rate:
  • Illustrative rental-coverage threshold:

Assumptions last reviewed: September 2026.

Actual lender calculations can differ and may include business accounts, adjusted profit, existing commitments, lease and tenant strength, property suitability and lender-specific criteria.
Ed Haupt Ed HauptManaging Director & Senior Mortgage Adviser

The Next Step

Want to Know What May Actually Be Available?

Your property, deposit and circumstances affect the options available. For business premises, we review the trading business; for investments, we consider rental income, the tenant and lease. We’ll explain which options may fit.

No obligation · Straightforward initial conversation

Figures are illustrative only and are not a mortgage offer, recommendation, affordability assessment or indication of approval. The interest rates and stress rates used are modelling assumptions only and are not current market rates being offered or recommended by Haupt & Co. Commercial mortgage rates, affordability assessments, loan-to-value limits and rental coverage requirements vary between lenders and individual circumstances. The calculation excludes valuation, legal, lender arrangement and other associated costs. Where costs are added to a loan, the amount borrowed and repayments may increase. Speak to us for an assessment based on your circumstances.
BEYOND PROPERTY

Funding equipment or vehicles too?

Property finance isn’t always the whole picture.

LENDING CRITERIA

What lenders check for each route

Owner-occupied commercial mortgage

Lenders will typically want to understand:

•  The trading business’s performance and ability to sustain the borrowing

•  The deposit or equity being put in

•  The suitability of the property itself

•  Your experience and ownership structure

Commercial investment mortgage

Lenders will typically want to understand:

•  The rental income and how it compares to the borrowing

•  The tenant’s covenant and lease terms

•  The deposit or equity contributed

•  Your experience as a landlord or investor

Both routes are assessed differently, and a case can sit somewhere between the two, for example where a business occupies part of a property and lets the rest. Worth mentioning early, rather than after an application is already underway.

TALK IT THROUGH

Not sure which category fits?

Not every lender treats every property type the same way, and some propositions are more specialist than others. If what you’re looking at doesn’t fit neatly into a category above, that’s a reason to talk to us, not a reason to assume finance isn’t available.

★★★★★
“They take the stress out of what can be a genuinely daunting process, explain everything in plain English, and always come back to you quickly.”
Jack Walsh · Google review

COMMON PITFALLS

What can derail a commercial mortgage?

Commercial mortgage applications can run into difficulties when important details are overlooked. Understanding what lenders look for can help you avoid these common pitfalls.

01

Assuming all lenders treat a given property type the same way.

02

Agreeing a purchase before establishing what’s realistically borrowable.

03

Focusing on the headline interest rate rather than the overall cost and suitability of the deal.

04

Underestimating valuation and legal requirements, and the time they take.

05

Leaving the ownership or borrowing structure until too late to change easily.

Speak to us early, while you’re still weighing up your options. We can help you understand what funding may be available and identify potential obstacles before you commit to a deal.

SECOND OPINION

Had a commercial mortgage declined?

A decline from one lender doesn’t necessarily mean the property can’t be financed. We can review what happened and look at whether it could work with another lender.

★★★★★
“Very helpful, understanding and knowledgeable”
Vic Saunders · Google review

Ed Haupt, independent mortgage broker in Bristol at Haupt & Co
MEET YOUR ADVISER

Managing Director & Senior Mortgage Adviser

Ed advises on commercial mortgages and complex lending across Bristol and the South West, working with limited companies, LLPs, sole traders and property investors. His focus is often on cases that don’t fit a standard template, including non-standard structures and situations where mainstream lenders have declined.

Haupt & Co Ltd (FCA No. 1043131) is an Appointed Representative of New Leaf Distribution Ltd, which is authorised and regulated by the Financial Conduct Authority (FCA No. 460421).

Ed founded Haupt & Co in 2025, following six years running a specialist mortgage practice. He manages cases from initial assessment through to drawdown.

WHY ADVICE MATTERS

Why Commercial Mortgages Often Need More Than a Rate Search

At a Glance
PropertyCommercial and semi-commercial property
PurposePurchase, refinance or release equity
BorrowerTrading businesses, individuals and companies depending on the proposition
Deposit / EquityThe amount required varies by lender, property and overall case
RepaymentCapital repayment or, where available and appropriate, interest-only
PricingRates and terms depend on the property, loan-to-value, business/borrower strength and overall risk

Commercial mortgage pricing matters, but the lowest advertised rate is only useful if the lender is suitable for the property, borrower and structure of the deal. Different lenders can take very different views of the same proposition.

HAUPT & CO VIEW

Our job is not simply to find a commercial mortgage rate. We assess which lenders are realistically interested in the proposition, compare the available options and help structure and present the application appropriately from the outset.

That can be particularly important where the property, business or ownership structure falls outside straightforward high-street lending.

WHY HAUPT & CO

Why Haupt & Co

We assess your plans, explain your options and manage your commercial mortgage application from the first conversation through to completion.

✓

Independent advice, compared across lenders

We compare suitable lenders based on your property, circumstances and funding needs.

✓

Clear explanations

Understand the costs, conditions and risks before deciding how to proceed.

✓

A properly prepared application

We bring together the information lenders need to assess your case.

✓

Support through to completion

We coordinate with the lender and keep you informed as your application progresses.

Our advice is grounded in experience, careful assessment, and a clear understanding of how commercial finance works in practice.

9.8out of 10, rated by clients on Verified Adviser
CASE STUDIES

Commercial Mortgage Case Studies

Examples of cases where the choice of lender made the difference. Each one was assessed individually.

Five offices and a flat, bought on rolling tenancies

SITUATION

The client was buying five offices with a buy-to-let flat attached, as an investment. The tenants were on rolling contracts, which left the remaining lease length short. Many lenders read that as weak income security.

APPROACH

We needed a lender prepared to assess the properties on expected future income rather than current lease terms. To give that lender comfort, we reviewed the client’s own income to confirm the borrowing could still be serviced if every tenant left before replacements arrived.

OUTCOME
Full mortgage offer secured

A trading company buys the building it works from

SITUATION

An established trading company wanted to buy its own premises. Its financial history was complicated, which reduced the number of lenders willing to consider the application.

APPROACH

We identified a specialist lender whose criteria suited the circumstances. Rather than rely on paperwork alone, we arranged a meeting on site with the client and the lender together, so the lender could see the business and hear the background first-hand.

OUTCOME
Lender offered during site visit

A small loan on a high-street restaurant and buy-to-let

SITUATION

The client needed to remortgage a high-street restaurant and a buy-to-let property. The loan was small, and that was the difficulty. Few commercial lenders will consider borrowing at this level, whatever the quality of the property or the business.

APPROACH

We identified a specialist lender that would assess the case on its merits, then managed the application through to offer. A smaller loan is not necessarily an easier one, and can need the same, if not more attention and energy. 

OUTCOME
Mortgage offer issued within 12 days

Dealing with something similar?

Client details have been anonymised. Every case is assessed individually, and outcomes cannot be guaranteed. 

How it Works

Our process is designed to keep things structured, transparent, and moving forward, with clear oversight at every stage.

Understanding a client's goals and objectives

Understand

A clear picture of your plans, timescale and funding needs.
Researching options across the whole of the lending market

Research & Advice

We compare suitable lenders and explain the options in plain terms.
Preparing and submitting a lender-ready application

Apply

We package the case and coordinate valuations and paperwork.
Managing an application through to completion

Support

We stay involved through to completion and help keep things moving.
What we'll cover in an initial conversation:

You’ll always know where things stand, what’s happening next, and who is managing each part of the process.

Commercial warehouse property in Bristol

Commercial Property Finance Across Bristol

Haupt & Co is based in the Bristol area and works with businesses and property investors seeking commercial mortgage finance across Bristol, North Somerset and the wider South West.

From trading premises and mixed-use buildings to offices, industrial units and commercial investments, the property itself can have a significant influence on which lenders are suitable.

Office building in Bristol's Temple Quarter

Central Bristol & Temple Quarter

Offices, mixed-use property, retail premises and commercial investment across the city centre and surrounding business districts.

Industrial logistics unit in Avonmouth

Avonmouth & Severnside

Industrial units, warehouses, logistics property and owner-occupied business premises.

Business park premises in North Bristol

North Bristol

Offices, business parks, industrial premises and trading property around areas such as Filton and Aztec West.

Retail units on a Bristol neighbourhood high street

Bristol Neighbourhood Centres

Retail units, mixed-use buildings and local trading premises across established areas such as Clifton, Gloucester Road and Bedminster.

We are not restricted to Bristol. Haupt & Co can arrange commercial property finance for suitable cases throughout the South West and across the UK.

GUIDES

Commercial Mortgage Guides

Practical guidance on buying, financing and refinancing commercial property.

RELATED GUIDES
FAQS

Commercial Mortgage FAQs

No two situations are the same. These are some of the questions we’re asked most often.

How do I know if commercial finance is the right option for me?

Commercial finance is typically suitable when funding is being used for business purposes rather than personal use, for example property purchases, refinancing, releasing capital, or funding growth (see the financing options above). We’ll help you assess whether commercial finance is the right fit and which route best matches your objectives and circumstances.

Most types of businesses can apply for a Commercial Mortgage, provided the borrowing is for business or investment purposes. This commonly includes limited companies, LLPs, partnerships, and sole traders, as well as property investment companies and trading businesses purchasing owner-occupied premises.

Professional practices, retail, hospitality, industrial, and manufacturing businesses are also commonly considered, subject to lender criteria. Each application is assessed on its own merits, taking into account the business structure, affordability, and the property being used as security.

Lenders mostly look at the purpose of borrowing, affordability, trading history, available security, and the overall structure of the deal (see ‘How lenders will look at your deal’ above for the full breakdown). Small details can materially affect outcomes, which is why early structuring and clear presentation are important.

We will review your circumstances and package your case appropriately for lender assessment.

Strong accounts can help, but they’re not the only factor. Some lenders place more emphasis on security, cashflow, or the underlying asset. We’ll be clear about what’s realistic based on your position and where flexibility may exist.

Not always. Fees, conditions, break clauses, and flexibility can have just as much impact over the life of the facility. Our role is to help you understand the full picture before committing.

There’s no fixed rate for commercial mortgages. Pricing depends on the property, the loan-to-value, the strength of the business or rental income behind the deal, and how the individual lender views the case, which is why commercial mortgages are usually priced on a case-by-case basis rather than a standard rate.

A stronger application with a lower LTV will generally attract more competitive pricing. Once we know a little about the property and how much you’d like to borrow, we can give you a realistic indication of the rates and costs available to you.

Many commercial mortgages are variable, with the rate linked to a base rate or other benchmark, and some lenders offer fixed rates.

Most commercial mortgage lenders require a deposit of between 25% and 40% of the property value, meaning you can typically borrow up to 70–75% LTV, depending on the lender, property type, and your business circumstances. Owner-occupied properties and stronger applications may access higher LTV options, while investment or specialist properties typically require a larger deposit. (Indicative only, as at September 2026. Lender criteria vary and can change without notice.) We’ll confirm likely deposit requirements for your situation at the first conversation.

You borrow against a commercial property, with the rest of the price covered by a deposit or equity. The lender assesses the business or the rental income and values the property before issuing an offer, while solicitors handle the legal work. The loan is repaid over an agreed term, usually on a capital and interest basis or, with some lenders, interest-only.

Minimum loan sizes vary widely by lender. Some high-street banks lend from £25,001, while many specialist lenders set minimums of £150,000 or more. Smaller loans can be harder to place, so fewer lenders will consider them. We look for lenders that will assess a smaller case on its merits.

Terms commonly run up to 25 years, and some lenders offer shorter terms from one or two years, depending on the lender, the property and the strength of the case. Some borrowers choose a shorter term and refinance later. Repayment is usually capital and interest, although some lenders offer interest-only, in which case the full loan is still due at the end of the term.

Typical costs include a valuation fee, your own legal costs and usually the lender’s legal costs, plus Stamp Duty Land Tax on a purchase in England and Northern Ireland (Scotland and Wales have their own property taxes). Arrangement fees may apply, and the amount varies by lender and product. Some products also carry early repayment charges. Our broker fee may also be payable. Before you commit, we explain every cost for your case, including the lender’s fees, legal costs, any early repayment charges, property taxes and our own fee, which we discuss with you at your consultation.

If the borrower is a limited company or LLP, lenders often ask the directors for a personal guarantee, particularly where the business is newer or the case is higher risk. A guarantee can make you personally liable if the company cannot repay, so take independent legal advice before you sign. Some guarantees are limited to an agreed amount and others are not.

No. A commercial mortgage is for property used for business, such as an office, shop or warehouse. A buy-to-let mortgage is for residential property let to tenants as homes. The lenders, criteria and sometimes the regulation differ, so it matters which one applies. If you are unsure, we will check before you apply.

Yes. Many borrowers refinance to improve terms, change the structure or release equity from property they already own. The lender reassesses the business and the property, and early repayment charges, valuation and legal costs can affect whether it is worthwhile. We review the numbers with you before you decide.

We stay involved throughout the process. This includes managing lender queries, coordinating valuations where required, and supporting you through to drawdown. We don’t disappear once the paperwork is submitted.

Timescales vary from case to case. Valuation, legal work and how quickly documents are supplied all affect how long a commercial mortgage takes. We help by checking your application before it goes to the lender, keeping in touch with the lender, valuer and solicitors, and updating you at each stage. Our guide to buying business premises in Bristol sets out the stages and where delays tend to happen.

Yes. Many commercial finance cases involve nuance, unusual property types, complex income, changing trading performance, or tight deadlines. We’ll assess the position honestly and outline the options available.

We compare suitable options across the market and explain the trade-offs clearly, allowing you to choose based on fit rather than being pushed towards a single solution.

You don’t need everything ready at the first conversation. Once we understand your requirements, we’ll outline what documentation is likely to be needed and in what order, so you can prepare efficiently.

Most commercial mortgages are not regulated by the Financial Conduct Authority in the way that residential mortgages are, because they’re taken out for business rather than personal purposes. Haupt & Co is an Appointed Representative of New Leaf Distribution Ltd, which is authorised and regulated by the FCA (FCA No. 460421), and we bring the same standard of advice to commercial cases regardless of their regulatory status.

CLIENT REVIEWS

What Our Clients Say

Posted on Google Google
Andrew Kingston profile picture
Andrew Kingston
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Haupt & Co are nothing short of amazing when it comes to mortgages! They really know their stuff, they keep you up to date every step of the way, they also provide service with a smile, which is hard to find these days! I’d highly recommend them to anyone 😀👍🏼
Posted on Google Google
Courtney Jaehme profile picture
Courtney Jaehme
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I received a fantastic service from Haupt & Co - they made the whole mortgage process as stress-free as possible from start to finish. So helpful, knowledgeable and responsive, always taking the time to explain everything clearly and find the best deal for us. Couldn't recommend them highly enough, thank you so much for all your help!
Posted on Google Google
Vic Saunders profile picture
Vic Saunders
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Very helpful, understanding and knowledgeable
Posted on Google Google
Richard Jaehme profile picture
Richard Jaehme
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I have used Haupt & Co for a number of remortgages now, Ed and his team always manage to beat the competition, when I cross-check their deals. Their customer service is excellent. I've also used them for life insurances, and Nick is fantastic at what he does. All of the team bring a very common-sense approach to their work, and they make things happen quickly. I would highly recommend.
Posted on Google Google
Jack Walsh profile picture
Jack Walsh
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Can't recommend Ed, Nick and Steph at Haupt & Co highly enough. I've used them a number of times now - across both my residential mortgage and my rental - and the service has been spot on every time. They take the stress out of what can be a genuinely daunting process, explain everything in plain English, and always come back to you quickly. If you need a mortgage broker in Bristol, these are the people to call.
Posted on Google Google
V R Heal profile picture
V R Heal
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Ed has helped me with a number of mortgages, buy to lets and residential. He is great to work with, really helpful and great advice. Would highly recommend.
Posted on Google Google
Tom Luke profile picture
Tom Luke
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Ed and Stef have been fantastic throughout the remortgaging of our house after a fixed term ended. They made it as stress free as possible and were completely clear about what was needed at every step as we went through. I have already recommended them to friends and family and will continue to do so!
Posted on Google Google
Jacob Flurry profile picture
Jacob Flurry
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Ed at Haupt & Co has been great every time my mortgage is up for renewal or if I have general financial queries in the property market. Always keeping me up to date with the best rates with my application and making the whole process as stress free as possible.
Posted on Google Google
Paul Infanti profile picture
Paul Infanti
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Ed and the team were amazing from start to finish. They recently helped us with our remortgage and are now arranging a mortgage for our daughter as well. Having access to the whole market really makes a difference, and the advice and process were completely seamless throughout. We can’t recommend them highly enough — 5⭐ plus!
Posted on Google Google
Claire Adams profile picture
Claire Adams
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Ed has always been very knowledgeable on all different mortgages be it residential ,hmo , btl , commercial , which having a diverse portfolio is exactly what I require . Also prompt with mortgage applications and updates while the mortgage proceeds. Always very happy to use this company .😊
READY WHEN YOU ARE

Let's Discuss Your Commercial Mortgage

Get in touch and we can let you know what’s potentially achievable for your situation.

★★★★★
“They really know their stuff, they keep you up to date every step of the way…”
Andrew Kingston · Google review

No obligation, just clear advice, and never rushed

Book a chatWhatsApp