First Time Buyer Mortgage Broker in Bristol
Buying your first home should feel exciting, not overwhelming.
- FCA Regulated
- 5 Star Google Reviews
- Access to 130+ lenders
- Bristol & South West based
Haupt & Co have been brilliant. Ed sorted our mortgage for our first home and honestly made the whole thing so much easier.
Michael Nguyen · Google review
Who our first-time buyer service is for
If you are buying your first home, we explain each step in plain English and answer your questions along the way.
Not sure if this is you?
That is what the first call is for. No obligation. It helps to have these to hand, but none is essential:
- A rough idea of your income and savings
- Details of any gifted deposit
- Your questions about the process
★★★★★
“Overall, a really trustworthy team who know what they’re doing. Would definitely recommend.”
Michael Nguyen · Google review
Real people.
Straight answers.
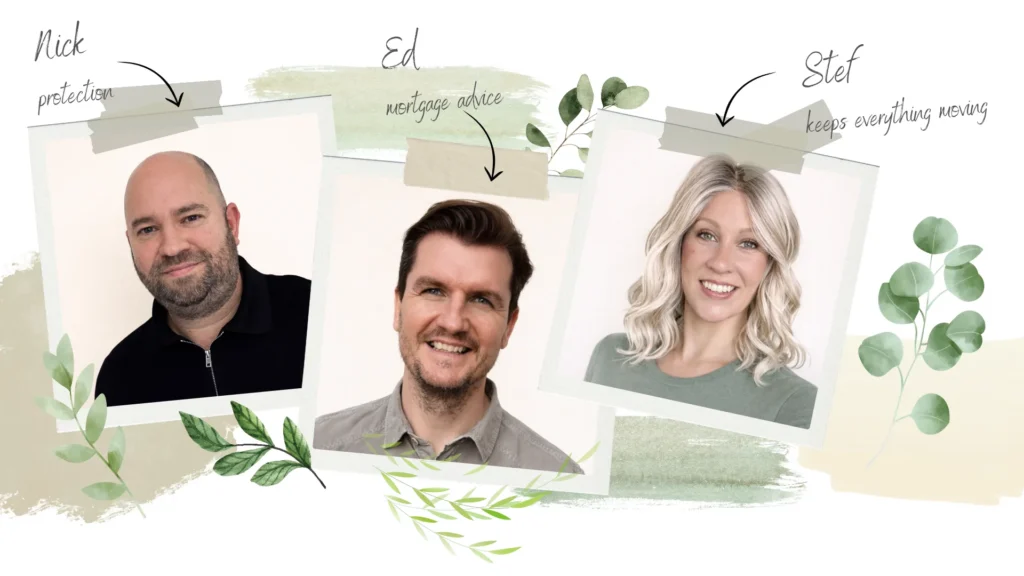
We’re a small team, which means you’ll know who you’re dealing with from the start. Familiar faces, straight answers and people who know and care about your case.
Independent client reviews
Read independent reviews from clients we’ve helped across the UK.
Here's how it works
Buying your first home is equal parts exciting and terrifying. We get it.
You’ll speak directly with Ed Haupt, our Senior Mortgage Adviser.
Here’s what we’ll do:
- Initial consultation: We will work out what you can borrow, how much deposit you need and whether you are ready to start looking. Take as long as you need, including a full hour with Ed if you would like one.
- Mortgage search: We search 130+ lenders to find rates you actually qualify for. We'll show you monthly payments and explain what you're signing up for.
- Application handling: We submit everything, chase the lender, and keep you updated. You'll know exactly where things stand.
- Completion: Once approved, we'll walk you through the final steps until keys are in your hand.
No jargon. No surprises. Just clear advice.
What lenders actually care about:
- Income: Can you afford the monthly payments? (They usually lend 4-4.5x your salary)
- Credit score: Have you paid bills on time? Missed payments hurt.
- Deposit: Where's the money coming from? (Gift from parents is fine, but needs documentation)
- Job stability: Been in your role 3+ months? Probation can be tricky but not impossible. We know which lenders are flexible on each of these. If one says no, we know who to try next.
Haupt & Co is a whole-of-market, FCA regulated Mortgage Broker, specialising in simple & complex lending.
In your free consultation we'll cover:
- What you can actually borrow
- Deposit needed (and whether a Lifetime ISA or an existing Help to Buy ISA helps)
- If your credit score is good enough
- What happens if you're self-employed or on probation
- Honest answer: are you ready, or should you wait?
Before you start house hunting
10 key things to know to help you make confident decisions.
Compare Widely
You’re not limited to first-time buyer mortgages. The right mortgage isn’t always a first-time buyer product. If you’re self-employed, see our self-employed mortgages page.
Stamp duty relief for first-time buyers
In England and Northern Ireland, first-time buyers pay no Stamp Duty Land Tax on the first £300,000 of a home costing up to £500,000. In Scotland, first-time buyer relief raises the Land and Buildings Transaction Tax nil rate band to £175,000. Wales has no first-time buyer relief. Rules can change, so check the current position with your solicitor.
Lifetime ISA
Know the property price cap and the 25% withdrawal charge if you go over it. Lifetime ISA rules may change, so check the current position with your provider.
You might be able to borrow more
Many lenders have more flexibility on affordability than before, so a “no” from one lender is not a “no” from all.
Self-employed? That's fine.
Lenders can consider irregular and variable income. How your income is evidenced matters.
Budget for the whole cost
Include survey, valuation, legal fees, stamp duty (if applicable) and moving costs.
Look at total cost, not just the rate
Consider fees, early repayment charges and what happens when the deal ends.
Get an agreement in principle first
It shows sellers you’re serious and gives you a realistic price range before you start viewing homes.
Tidy your credit file early
Check your report, correct errors, and register on the electoral roll.
Protect your home. Don't just buy it
Consider life insurance, critical illness cover, and income protection.
We are here to help with practical and honest advice based on your circumstances.
What Our Clients Say
 Posted on Google

 Andrew Kingston
Trustindex verifies that the original source of the review is Google.
Haupt & Co are nothing short of amazing when it comes to mortgages! They really know their stuff, they keep you up to date every step of the way, they also provide service with a smile, which is hard to find these days! I’d highly recommend them to anyone 😀👍🏼Posted on Google Courtney JaehmeI received a fantastic service from Haupt & Co - they made the whole mortgage process as stress-free as possible from start to finish. So helpful, knowledgeable and responsive, always taking the time to explain everything clearly and find the best deal for us. Couldn't recommend them highly enough, thank you so much for all your help!Posted on Google
 Vic SaundersVery helpful, understanding and knowledgeablePosted on Google
 Richard JaehmeI have used Haupt & Co for a number of remortgages now, Ed and his team always manage to beat the competition, when I cross-check their deals. Their customer service is excellent. I've also used them for life insurances, and Nick is fantastic at what he does. All of the team bring a very common-sense approach to their work, and they make things happen quickly. I would highly recommend.Posted on Google
 Jack WalshCan't recommend Ed, Nick and Steph at Haupt & Co highly enough. I've used them a number of times now - across both my residential mortgage and my rental - and the service has been spot on every time. They take the stress out of what can be a genuinely daunting process, explain everything in plain English, and always come back to you quickly. If you need a mortgage broker in Bristol, these are the people to call.Posted on Google
 V R HealEd has helped me with a number of mortgages, buy to lets and residential. He is great to work with, really helpful and great advice. Would highly recommend.Posted on Google
 Tom LukeEd and Stef have been fantastic throughout the remortgaging of our house after a fixed term ended. They made it as stress free as possible and were completely clear about what was needed at every step as we went through. I have already recommended them to friends and family and will continue to do so!Posted on Google
 Jacob FlurryEd at Haupt & Co has been great every time my mortgage is up for renewal or if I have general financial queries in the property market. Always keeping me up to date with the best rates with my application and making the whole process as stress free as possible.Posted on Google
 Paul InfantiEd and the team were amazing from start to finish. They recently helped us with our remortgage and are now arranging a mortgage for our daughter as well. Having access to the whole market really makes a difference, and the advice and process were completely seamless throughout. We can’t recommend them highly enough — 5⭐ plus!Posted on Google
 Claire AdamsEd has always been very knowledgeable on all different mortgages be it residential ,hmo , btl , commercial , which having a diverse portfolio is exactly what I require . Also prompt with mortgage applications and updates while the mortgage proceeds. Always very happy to use this company .😊
Lenders look at self-employed income differently, so how your income is presented matters. Our self-employed mortgages page explains what to expect.
Many first-time buyers look at life and income protection alongside their mortgage. Our protection page explains the options.
Our residential mortgages page explains how we help when you are buying a home.
Want more information on first-time buyer mortgages?
If you’re looking for first time buyer mortgage advice in Bristol, here is a clear, honest look at what it actually takes to buy your first home in 2026: what the market looks like, what it costs, and how to know if you are ready.
First Time Buyer FAQs
No two situations are the same. These are some of the questions we’re asked most often.
MONEY
How much could I borrow as a first-time buyer?
Many lenders base the amount on a multiple of your income, and some will lend more in certain cases, but this usually depends on strong credit, low outgoings, and a solid deposit. Income isn’t the only factor lenders consider, they also look at your spending, existing debts, and overall affordability. Just because a lender may offer a higher amount doesn’t mean it’s the right choice, and we’ll help you work out what’s realistic, comfortable, and sustainable for you.
How much deposit do I need to buy my first home?
Many first-time buyers assume they need a huge deposit, but that isn’t always the case. Here in the UK, deposits typically start from around 5% of the property price, with 10% or more often giving access to better rates. The right deposit for you depends on your budget, the property, and what lenders are offering at the time. We’ll help you understand what’s possible and work out what makes the most sense for your situation, not just what looks good on paper.
Can my parents help me with a deposit?
Yes, this is very common. Parents can help by gifting some or all of the deposit. Most lenders are happy with this, as long as the money is a genuine gift and not a loan that needs to be repaid. Your parents will typically need to sign a short declaration confirming this, and we’ll guide everyone through what’s required.
What do lenders need to see if my deposit is a gift?
Lenders and your solicitor will usually need a letter signed by the person giving the money. It confirms the money is a gift, that it does not need to be repaid and that they have no claim on the property. Many lenders only accept gifts from close family such as parents, grandparents or siblings, and policies vary, so we check this before you apply. The gift must be declared to both your lender and your solicitor. If you or the person giving the money have questions about inheritance tax, speak to a solicitor or accountant.
Can I buy a home if I have student loans?
Yes, having a student loan doesn’t automatically stop you from getting a mortgage. Lenders will look at your overall affordability, including your income and any regular financial commitments. Student loan repayments are taken into account alongside other outgoings, so we’ll make sure this is factored in when assessing how much you can borrow and which lenders are most suitable for your situation.
What other costs should I budget for besides the deposit?
In addition to your deposit, there are other costs to consider such as legal fees, surveys, mortgage fees, and moving costs. Planning for these early helps avoid surprises later on. We’ll help you build a clear picture of the full cost of buying, so you can move forward feeling financially prepared. Speak with a Mortgage Broker
Do first-time buyers pay stamp duty?
It depends on where you are buying. In England and Northern Ireland, first-time buyers pay no Stamp Duty Land Tax on the first £300,000 of a home costing up to £500,000, and 5% on the part between £300,001 and £500,000. The relief does not apply above £500,000. In Scotland, first-time buyer relief raises the Land and Buildings Transaction Tax nil rate band to £175,000. Wales has no first-time buyer relief under Land Transaction Tax. Rules can change, so check the current position with your solicitor.
Can I use a Lifetime ISA to buy my first home?
In many cases, yes. You can use a Lifetime ISA towards a first home without the 25% withdrawal charge if the property costs £450,000 or less, you are buying with a mortgage and the account has been open for at least 12 months. Withdrawing the money for other reasons usually triggers the charge. Rules can change, so check the current position with your Lifetime ISA provider.
What if my credit history isn’t perfect?
You’re not alone. Many first-time buyers have something on their credit file. Minor issues don’t necessarily mean you can’t get a mortgage, but they do affect which lenders are suitable. We’ll review your credit profile with you and help identify lenders who are more flexible, explaining your options clearly before you apply.
Why do lenders focus so much on income and credit when I’ve been paying rent for years?
This is a very common frustration. While rent payments show you can manage regular housing costs, lenders are required to assess affordability using income, credit history, and wider financial commitments. The good news is that different lenders take different views, and understanding how to present your situation properly can make a real difference, and that’s where our expert advice helps.
PROCESS
Why is it helpful to speak to a mortgage adviser before I start viewing homes?
Many first-time buyers start looking at properties before fully understanding what they can borrow, which can lead to disappointment or wasted time. Speaking to a mortgage adviser early helps you understand your realistic budget, monthly costs, and options before you fall in love with a property. It also means you’ll be better prepared and taken more seriously when you’re ready to make an offer.
Do I need a mortgage agreement before I start viewing properties?
In most cases, yes. A mortgage agreement in principle often referred to as a DIP (Decision in Principle), AIP (Agreement in Principle), or MIP (Mortgage in Principle) gives you an early indication of how much you could borrow and shows estate agents that you’re a serious buyer. It doesn’t lock you into anything and can usually be updated as your plans change. We can arrange this quickly and explain exactly what it means (and what it doesn’t), so you can start viewing with confidence.
What documents will I need to provide to you?
There can be a few documents involved, but don’t worry, we’ll clearly explain what’s needed, why it’s required, and guide you through it step by step. The exact documents can vary depending on your circumstances, but typically we’ll ask for:
Photo ID (passport or driving licence)
Proof of address (recent utility bill or bank statement)
Last 3 months’ payslips (or accounts / SA302s if you’re self-employed)
Recent bank statements (usually the last 3 months for all accounts you have both personal and joint)
Details of any existing credit commitments (loans, credit cards, car finance etc.)
Proof of deposit (savings statements or gifted deposit confirmation)
- Credit Report
Property details (once you’ve found one)
If anything else is needed, we’ll explain exactly what’s required and why and help you get it together without stress.
How long does the buying process usually take for first-time buyers?
The timescale can vary, but for most first-time buyers the process typically takes around 8 to 12 weeks from having an offer accepted to completing on the property.
This includes time for the mortgage application, valuation, legal work, and any searches required by your solicitor. Some purchases move more quickly, while others can take longer depending on factors such as the property, the lender, and how smoothly the legal process progresses.
Our role is to help keep things moving, manage the mortgage side of the process, and keep you informed throughout so there are no unnecessary delays or surprises.
Do I need to use the estate agent’s mortgage adviser?
No, you’re free to choose your own mortgage adviser. While estate agents may recommend someone, it’s important to work with an adviser who searches the whole market and puts your interests first. We’ll provide independent, whole-of-market advice and support you throughout the process.
Related reading
Already looking at properties? Read our guide to the 7 questions to ask an estate agent before making an offer, including what to ask about probate, leasehold and EWS1 before you commit.
Practical guidance for first-time buyers on saving, borrowing and buying your first home.
First-Time Buyer Guide 2026: Are You Closer to Buying Than You Think?
A practical guide for first-time buyers covering affordability, deposits, mortgage options and the key steps to getting ready to buy your first home.
Are You Ready?
If buying now isn’t right for you, we’ll tell you and help you plan instead.
You may be ready
- Around 5% or more saved for a deposit
- Typically 3+ months in your job (1+ year if self-employed)
- A healthy credit history
- Monthly payments that feel manageable, often under 30% of take-home pay
You'll leave knowing what to do next, with no pressure
General guidance only, not requirements set by every lender. Eligibility depends on your individual circumstances and each lender's own criteria.
You may need a little more time
- Recent missed payments on your credit file
- A recently started job
- A deposit of less than 5%
- Monthly payments that may be above 30% of take-home pay
You'll leave knowing what to do next, with no pressure
General guidance only, not requirements set by every lender. Eligibility depends on your individual circumstances and each lender's own criteria.
Not sure where you stand?
That’s exactly what the first call is for. We will tell you honestly whether you are ready or what needs to happen first, and you can take as long as you need.
Let's Start Getting You Home Ready
No obligation, just clear, supportive advice